A single incident can affect far more than one vehicle or one shift. For a non-emergency medical transportation operator, a collision, passenger injury allegation, missed trip dispute, or data breach can place contracts, fleet availability, and enterprise value under pressure at the same time. Medical transport insurance is therefore not simply a compliance purchase. It is a core control within the operating model.
For NEMT businesses, insurance has to reflect the real conditions of service: mobility-impaired passengers, wheelchair securement, recurring healthcare trips, subcontracted capacity, demanding payer requirements, and drivers working across long operating days. The strongest programs connect coverage decisions to safety practices, fleet technology, contract management, and growth strategy.
Medical Transport Insurance Is an Operating Requirement
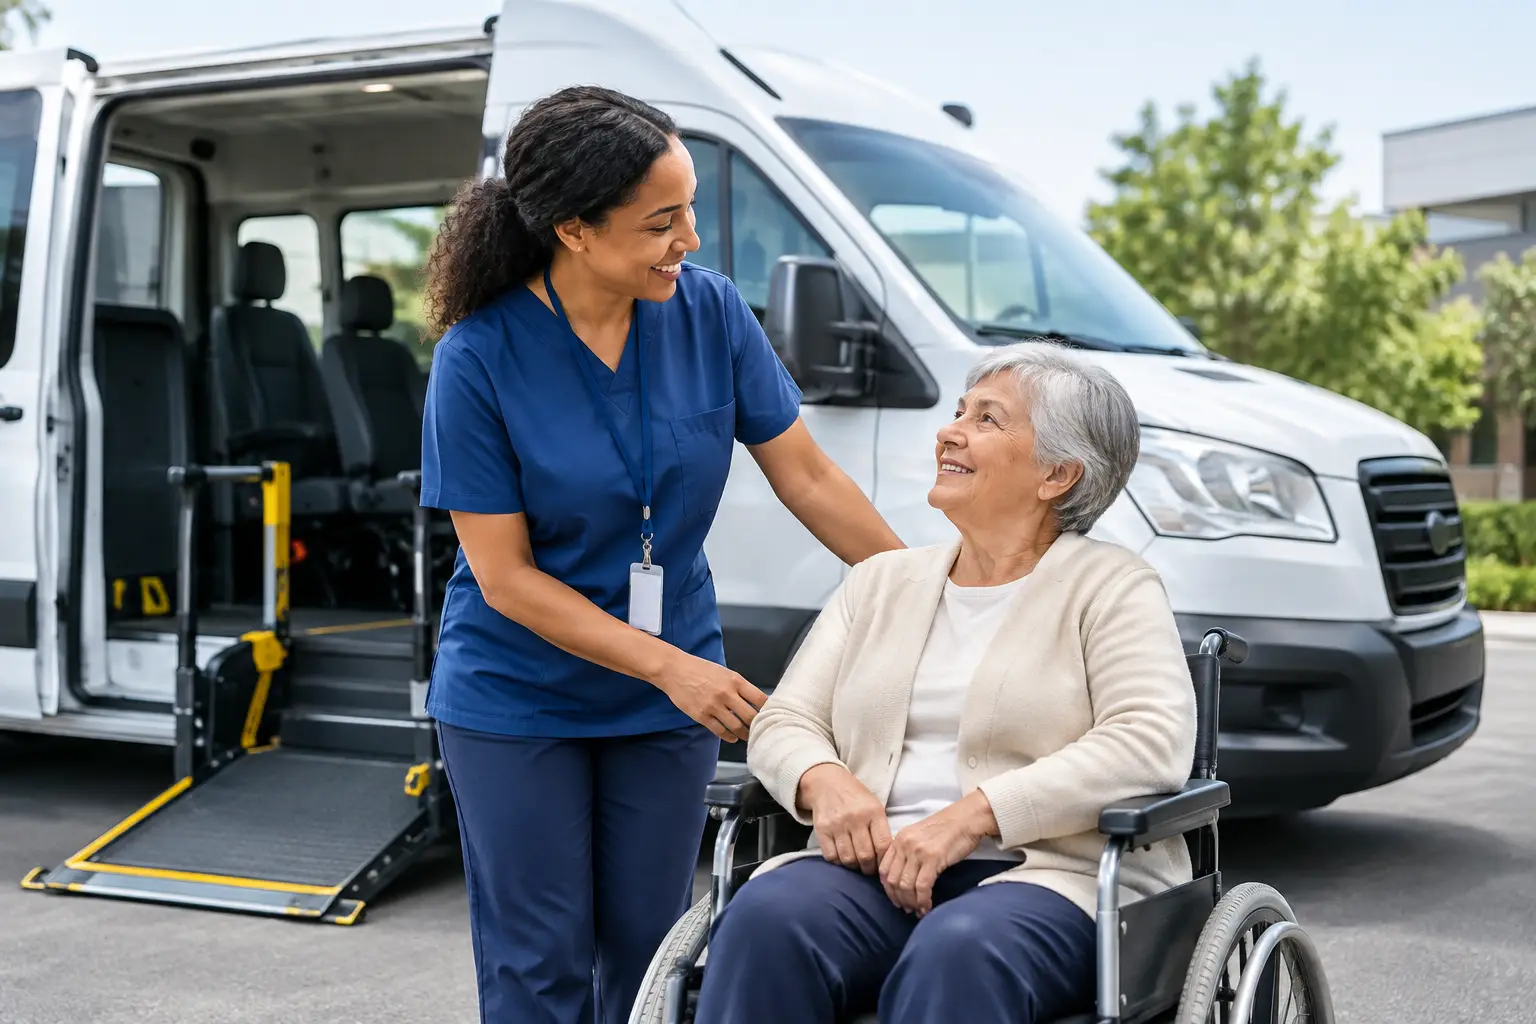
Standard personal or light commercial auto coverage is rarely designed for the exposure profile of a medical transportation operation. NEMT fleets carry passengers who may have significant mobility, cognitive, or medical needs. A relatively routine vehicle incident can become a complex claim when a passenger requires assistance entering the vehicle, uses a wheelchair, or alleges an injury during transport.
Insurance requirements also differ by operating market. State regulators, Medicaid programs, managed care organizations, hospitals, brokers, and private facilities may each impose specific limits, endorsements, certificate language, or notification obligations. An operator that treats insurance as an annual administrative renewal can discover too late that its coverage does not satisfy a new contract or that a lapse threatens reimbursement eligibility.
The practical objective is broader: maintain a coverage structure that supports safe service delivery, protects balance-sheet stability, and allows the business to keep operating when a loss occurs. This requires leadership involvement, not only a conversation between an insurance broker and a back-office administrator.
The Coverage Foundation for Medical Transportation
The appropriate policy mix depends on fleet size, service territory, passenger profile, vehicle type, payer mix, and whether the company uses employees, owner-operators, or subcontractors. Still, several coverage categories form the typical foundation for a professionally managed NEMT operation.
Commercial auto liability addresses bodily injury and property damage arising from vehicle operations. Limits should be evaluated against contract minimums, local litigation conditions, passenger exposure, and the potential severity of a multi-party incident. The lowest available limit may meet a basic requirement while leaving the business exposed to a claim that exceeds its retained protection.
Physical damage coverage protects owned vehicles against collision, comprehensive losses, theft, vandalism, and certain weather events, subject to deductibles and policy terms. It matters especially when replacement vehicles are difficult to source or when a specialized wheelchair-accessible vehicle represents a substantial capital investment. Operators should compare the policy valuation method with replacement costs, not merely the book value shown in internal records.
General liability can respond to third-party injury or property damage claims that do not arise directly from vehicle use. Depending on operations, this may include incidents at an office, facility, or loading area. Professional liability or errors and omissions coverage may also be relevant where contractual responsibilities, scheduling decisions, dispatch practices, or alleged service failures create a distinct exposure.
Workers' compensation protects the workforce and is central to operational continuity. Drivers and attendants face risks from lifting, assisting passengers, operating wheelchair lifts, securing mobility devices, and working around traffic. A program that focuses only on claims cost without addressing training, ergonomic practices, and return-to-work procedures misses the larger workforce issue.
Cyber liability deserves increasing attention. Dispatch systems, trip records, customer contact information, payment data, and healthcare-related information create potential exposure. A ransomware event or unauthorized system access can interrupt service even if no vehicle is involved. Coverage should be reviewed alongside the company’s data governance, access controls, backup practices, and incident-response procedures.
Many operators also need umbrella or excess liability coverage to provide limits above underlying policies. Hired and non-owned auto coverage can be necessary when employees use personal vehicles for business purposes or when the business relies on rented vehicles. If subcontractors provide trips under the company’s name, their insurance requirements, certificates, and indemnity commitments should be actively managed rather than collected once and filed away.
Where Coverage and Operations Meet
The best medical transport insurance program cannot compensate for weak operational controls. Underwriters, payers, and prospective acquirers increasingly look for evidence that an operator understands its loss drivers and manages them consistently.
Driver qualification is one example. A documented process for motor vehicle record review, background screening, training, coaching, and remedial action provides a stronger risk profile than informal hiring practices. The same applies to wheelchair securement training, lift operation, defensive driving, passenger-assistance protocols, and incident reporting. These controls reduce risk, but they also create a record of responsible management after a claim.
Fleet technology adds another layer of visibility. Telematics, dash cameras, electronic vehicle inspections, maintenance platforms, and digital dispatch systems can help operators identify hard braking, speeding, missed inspections, route deviations, and equipment issues before they become claims. Technology is not a substitute for leadership judgment. It is an operating system for applying that judgment with timely data.
Claims management should be treated as a defined workflow. Drivers need to know whom to contact, what information to collect, when to preserve video, and how to document passenger conditions without making unnecessary statements about fault. Management should review every significant incident for both immediate response and root cause. A claim involving a wheelchair securement issue, for example, may reveal a training gap, an equipment maintenance issue, or a dispatch practice that does not allow sufficient loading time.
Insurance Readiness for Contracts and Transactions
For operators pursuing managed care, hospital, or government-funded work, insurance is often a gatekeeping requirement. Certificates of insurance may be needed before service begins, and contract terms can require additional insured status, waiver of subrogation, specific limits, or advance notice of cancellation. These requirements should be reviewed before signing, because some obligations may be difficult or expensive to add after the fact.
Operators considering a sale or strategic partnership should view insurance through a diligence lens. A buyer will typically assess loss runs, open claims, reserve development, policy history, coverage limits, safety documentation, vehicle maintenance records, and subcontractor controls. Unresolved claims or inconsistent records can slow a transaction, reduce confidence in projected earnings, or require additional indemnity negotiations.
This is where an integrated transportation platform can create practical value. NextGen Mobility’s operating perspective across medical transportation, passenger transportation, and fleet technology reflects a simple principle: risk management improves when insurance, safety, maintenance, and data are managed as connected functions rather than separate departments.
Building a More Defensible Insurance Program
An annual renewal is a useful checkpoint, but it should not be the only time leadership examines risk. A disciplined review starts with current operations: fleet inventory, vehicle use, passenger assistance practices, geographic footprint, staffing model, major contracts, subcontractors, and technology systems. Any material change in these areas may require a coverage adjustment.
Loss runs deserve careful attention. Look beyond premium and claim count to identify patterns by driver, vehicle, service area, time of day, claim type, and root cause. A rise in minor backing incidents may call for camera adoption or yard procedures. Repeated passenger injury allegations may warrant a review of securement equipment, attendant training, trip timing, and documentation standards.
The broker relationship matters, but the operator should retain ownership of the risk narrative. Provide accurate operational data, ask how exclusions apply to actual services, and confirm that policy forms align with contractual obligations. If coverage is being placed through multiple carriers, verify that there are no gaps between policies. Lower premiums can be valuable, but only when the resulting structure still protects the operation that exists today.
Insurance also benefits from board-level or executive-level visibility. Leaders should understand the organization’s retained risk, deductible exposure, major claims, renewal outlook, and compliance obligations. That discipline makes it easier to allocate capital, evaluate new contracts, and decide whether expansion into a new geography or service line fits the company’s risk appetite.
A capable medical transportation business earns confidence through predictable operations. When insurance is aligned with disciplined safety systems, reliable fleet data, and clear accountability, it becomes more than a policy file. It becomes part of the infrastructure that helps an operator protect passengers, preserve contracts, and make informed decisions about growth.